
© Urenkoff 2025
Both of these products will tell you they automate reconciliation, and both are telling the truth. They are solving it from opposite ends. One starts from the close and works back to the transactions. The other starts from the money and stops before the close begins.
This article compares two pieces of reconciliation software and sets out what each one does, where they genuinely overlap, and the questions that usually decide it. Everything described here about FloQast comes from FloQast's own published product material, which is linked at the end so you can check any of it yourself.
The difference in one line
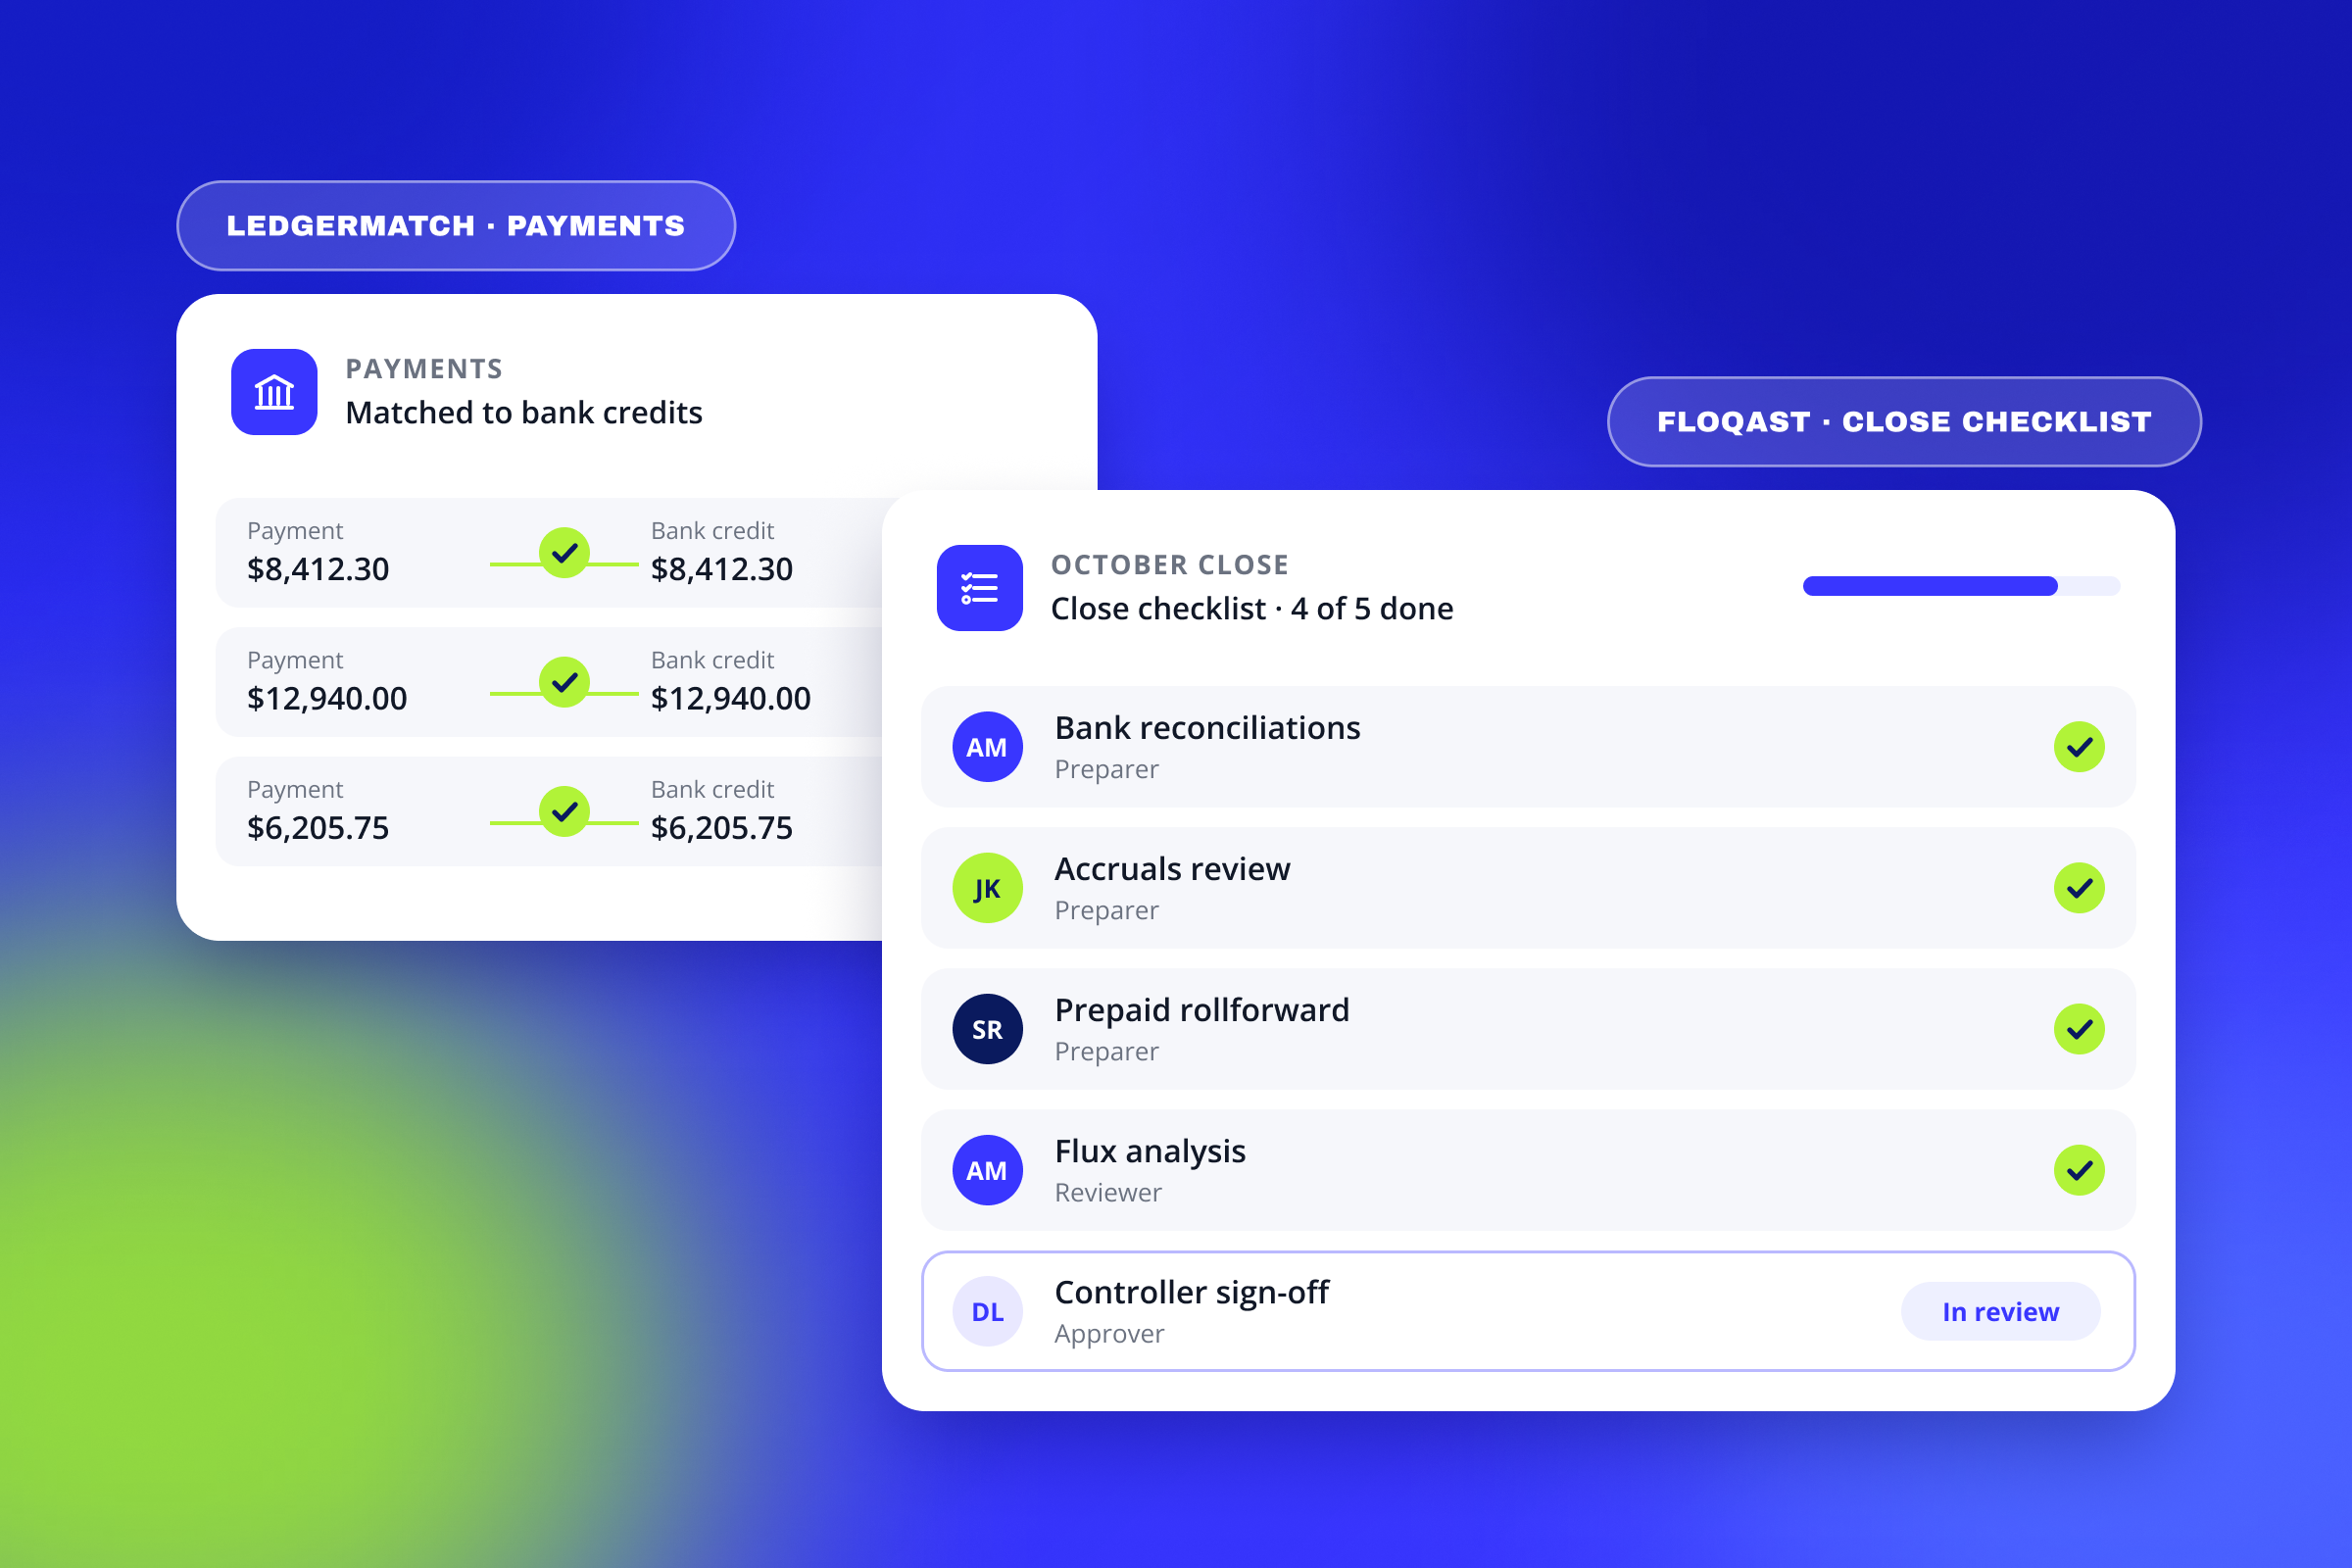
LedgerMatch, the reconciliation software built by Urenkoff, is a matching product. It concentrates on money coming in: payments, card settlements and deposits, checked against what actually arrived in the bank, with the exceptions passed to a person. It does not manage your close and it does not post to your ledger.
FloQast is a close management platform. It organises the month-end close, with reconciliations, matching, journals and compliance work managed inside it, and it posts adjusting journals back to your ERP. Its own description is "designed by accountants for accountants", which tells you precisely who it is built around.
Neither description is a criticism of the other. A close platform is supposed to run the close. A matching product is supposed to match. The question is which half of the problem is costing you more right now.
What LedgerMatch does
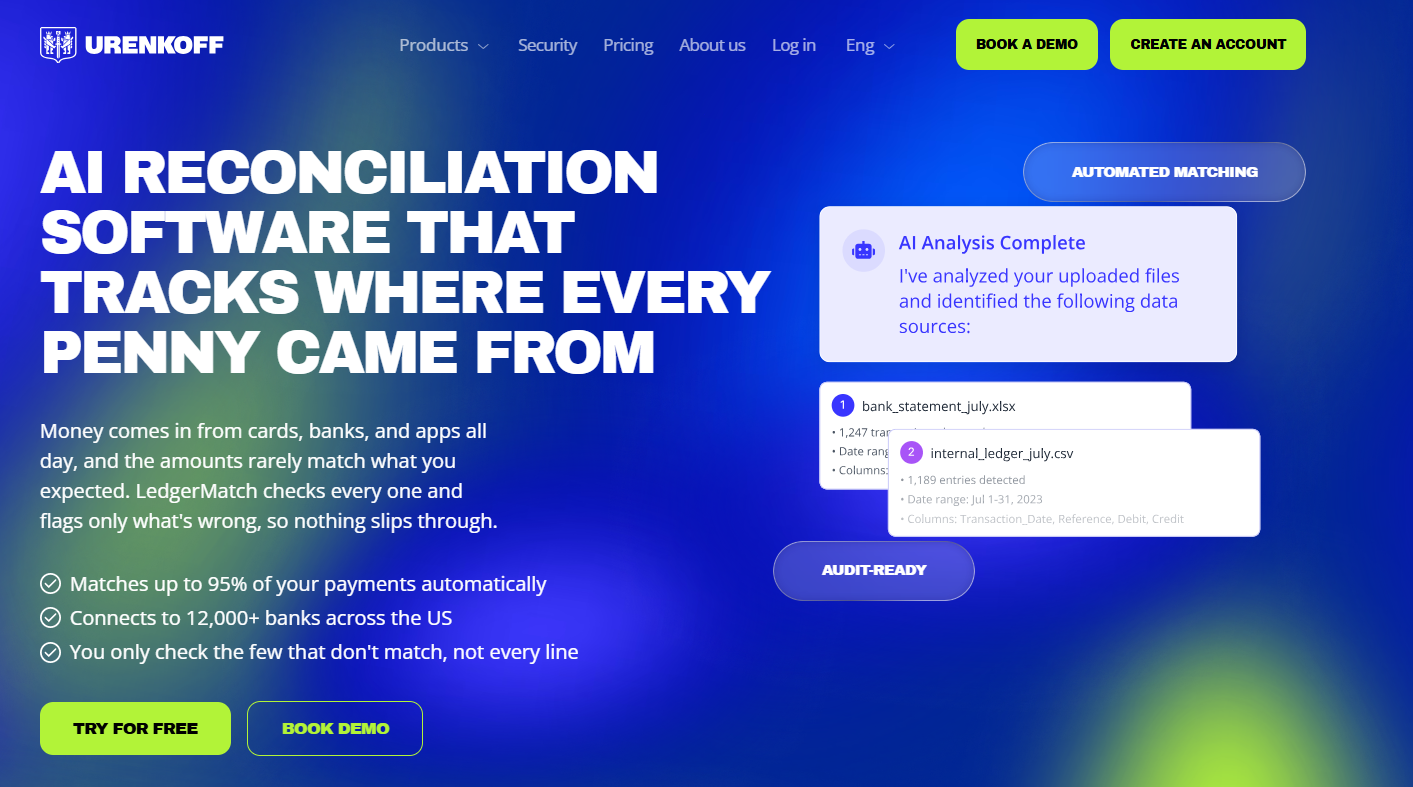
LedgerMatch, Urenkoff's reconciliation software, is built around one question: did the money you were owed actually arrive, and if some of it did not, which payments and why. It reads what your systems say you should have received and what the bank actually received, matches the two, and sends a person only the items that do not reconcile.
The part that matters most to a finance team is how differences are handled. Fees, rounding and settlement timing are applied during matching rather than left as variances for somebody to investigate, so what reaches a person is genuinely unexplained. Ambiguous items are deliberately left unmatched rather than force-matched, because a wrong match costs more later than an open one does now.
It is also deliberately narrow. LedgerMatch does not run your close, does not manage a checklist, does not certify accounts and does not write to your ERP. It produces a checked figure and the evidence behind it, and your existing process takes it from there.
What FloQast does
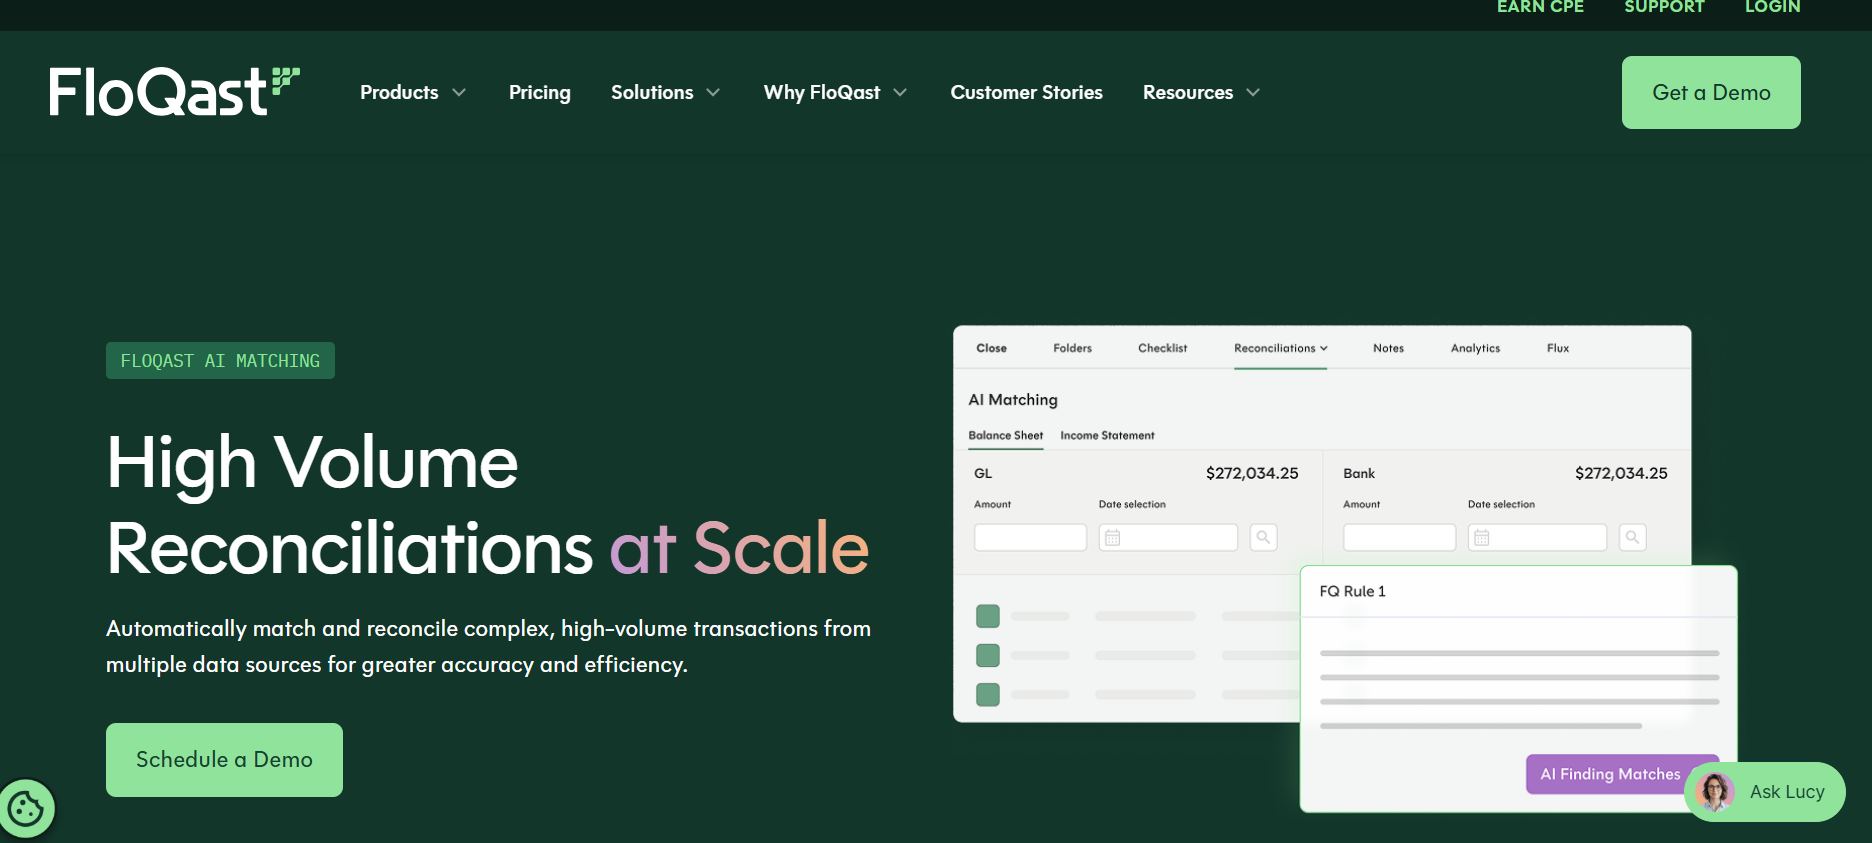
FloQast starts where the accountant starts: the close checklist. Its subject is the whole month-end process, with reconciliations, matching, journals and compliance work managed in one place and tied back to the ERP. Matching is one capability inside that, rather than the product itself.
Two things in that table deserve underlining, because they are the real difference. FloQast posts adjusting journals directly to your ERP, which closes the loop between matching and accounting. And it carries the apparatus of a close: rollforward schedules, auto-certification within thresholds, and the checklist that tells a team what is done and what is not. FloQast states it is trusted by more than 3,500 global companies.
It is also honest about its audience. "Designed by accountants for accountants" is not marketing filler, it is an accurate description of the product's shape. The workflow assumes a controller, an accounting manager and a close calendar.
Where the two genuinely overlap
This is a closer comparison than it first looks, and it is worth being straight about that. Both products:
- Automate transaction matching at high volume
- Match bank and card activity against your own records
- Let you configure matching rules rather than accept fixed logic
- Route exceptions to a person instead of making someone review everything
- Keep an audit trail behind matched items
- Publish an upper-bound automation figure
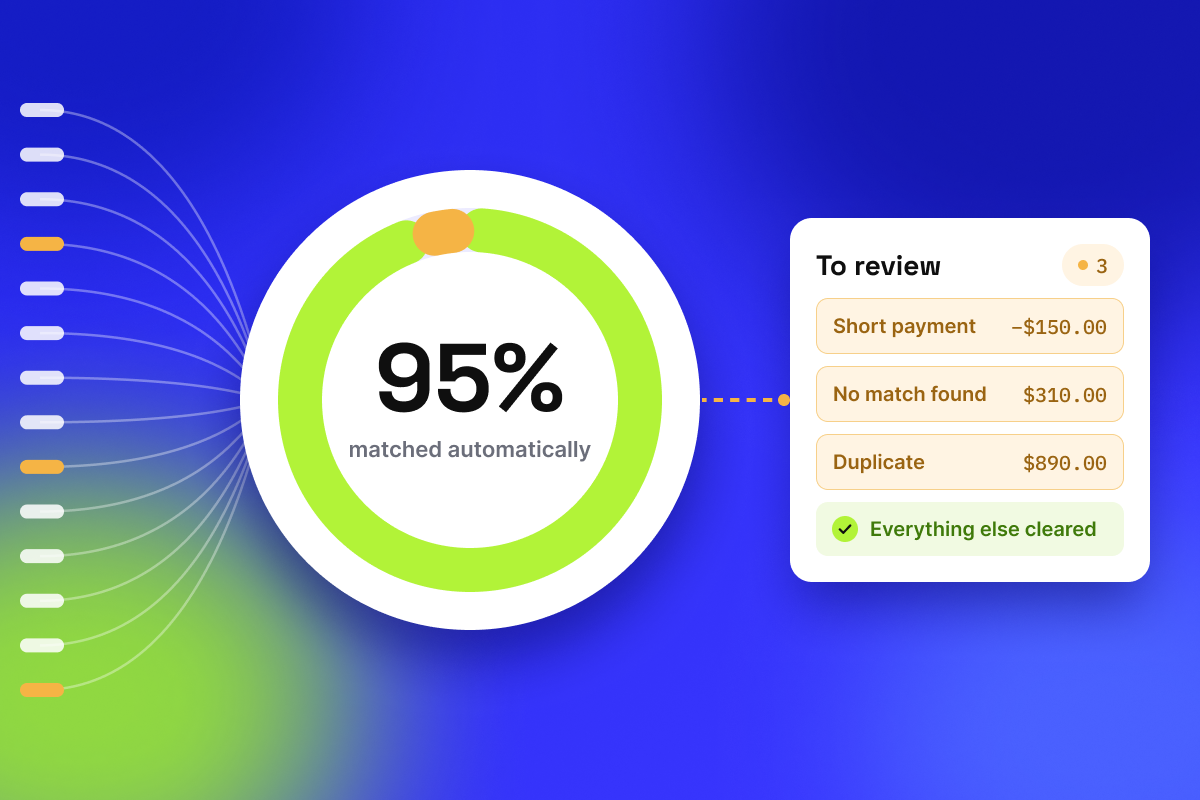
A word about those two figures. FloQast states that AI rules reconcile up to 98% of transactions. LedgerMatch states that up to 95% of payments are matched automatically. Those numbers are not measured on the same population. One covers transactions inside a close process across general ledger and subledger data, the other covers incoming payments matched against bank credits. Reading them as a league table would be a mistake, and we would say the same if the numbers ran the other way. The useful question is not whose figure is higher on a website, but what the unmatched remainder looks like in your own data, which only a test on your own period will answer.
The differences that decide it
1. Where the product starts. FloQast starts at the close checklist and works down to the transactions. LedgerMatch starts at the bank and stops once the money is confirmed. That single difference explains most of the others.
2. What sits on the other side of the match. LedgerMatch matches payments to money that landed in the account. FloQast matches ledger and subledger activity to bank and card data as part of closing those accounts.
3. Whether anything is written back. FloQast can generate, validate, approve and post adjusting journals directly to your ERP. LedgerMatch posts nothing anywhere. One closes the loop into accounting, the other hands you an answer and leaves your systems untouched.
4. Whether you need an ERP. FloQast's value is tied to the systems it integrates with, and its named integrations are ERP platforms. LedgerMatch reads banks and processors directly and does not assume an ERP sits underneath.
5. Who the product is shaped around. FloQast is designed for accountants running a close calendar. LedgerMatch is shaped around whoever is responsible for money arriving correctly, which in a retailer, a marketplace or an ecommerce business is often not the controller at all.
6. How buying works. LedgerMatch publishes its prices and offers a free tier and a trial. FloQast does not publish prices and directs buyers to request a quote, which is normal for platform software sold to accounting teams and means the process starts with a conversation.
Which difference matters to you
Side by side
Every row is drawn from the two companies' own published material. Neither column is a scorecard, and several rows that look like a gap are simply a description of what that product is for.
They are not mutually exclusive
These two sit at different points in the same pipeline, which means some finance teams will genuinely want both. Confirming what arrived from your banks and processors happens before the close; organising, certifying and documenting that close happens after. A company running FloQast may still have an incoming payment problem it has not solved, and a company using LedgerMatch may later want its close managed properly.
If you are weighing them as alternatives, check first whether you are comparing two answers to the same question.
Five questions that will decide it for you
- What is slow right now? Matching the transactions, or running and documenting the close around them?
- What are you matching? Payments, settlements and bank credits, or ledger and subledger balances?
- Do you want journals posted automatically? If the answer is yes, that points firmly one way.
- Do you run an ERP the platform integrates with? If not, a close platform loses much of its advantage.
- Who will own this day to day? A controller closing the books, or a team responsible for money arriving correctly?
What to ask on the call, whichever way you are leaning
The same five questions work on us and on anyone else you are evaluating, and the answers tell you more than a feature list.
- What exactly will this match, and what will still land on a person's desk?
- What does it connect to directly, and what will we have to upload ourselves?
- What does your published automation figure actually measure, and on what kind of data?
- What has to be decided internally before configuration can start?
- Can we run it against a period we have already closed, and compare both answers?
The third and fifth are the ones worth insisting on. An upper-bound percentage means very little until you know what it was measured on, and any vendor confident in its matching should be happy to be checked against a month you already know the answer to.
See it against your own numbers
The fastest way to settle any of this is to run a period you have already closed. Book a walkthrough and we will match a month your team has already reconciled, so you can compare what LedgerMatch says against the answer you reached yourself, before anything depends on it.
Become a Design Partner
Reconcile faster. Stay audit-ready
We're accepting a limited number of organizations for the inaugural cohort. No cost, 12 months, direct access to our team.
General
General
November 11, 2026
How to Audit a Bank Reconciliation
A bank reconciliation that balances proves almost nothing. This guide covers the full audit procedure, the manipulations it catches, and the red flags worth knowing.
General
General
November 11, 2026
How to Connect Your Business Bank Account for Automatic Reconciliation
Title Post for ES Version
Connecting your bank account directly is what makes daily reconciliation possible, instead of exporting a statement once a month. This guide covers what the connection actually gives a vendor, the six questions to ask before you authorise one, and how to test the result against a month you have already closed.
Post Summary for ES Version
General
General
November 11, 2026
How to Reconcile Accounts Receivable Without Forcing the Numbers
Accounts receivable reconciliation answers one question: does what customers owe you agree with the money that actually arrived. This guide covers the six-step process, the six differences that cause most of the work, and how to stop doing the matching by hand.